

If you want to see the target analysis for bull and bear cases again, you can go back to my weekly analyses of the last 3 weeks and find them there.
As I have mentioned in the past, I am not a huge fan of Elon Musk, as he is a master hand-waver, and seems to shift gears on a whim if it fits what he desires. The one thing he has made sense of is this item. Commercial real estate is in peril. This article covers residential real estate too, and perhaps another time I will discuss that issue, which is way more complex than many think, at a later time.
If the Fed continues to raise rates, putting pressure on the value of its treasury bond portfolio, that could trigger a fire sale and a potential collapse of these regional banks. One thing people should realize, however, is that regional banks are actually the third largest holders of construction loans. Read this article from somewhat left-leaning Axios. It does get the central data points right. Here is the article, and below is the chart from Moody’s Analytics:
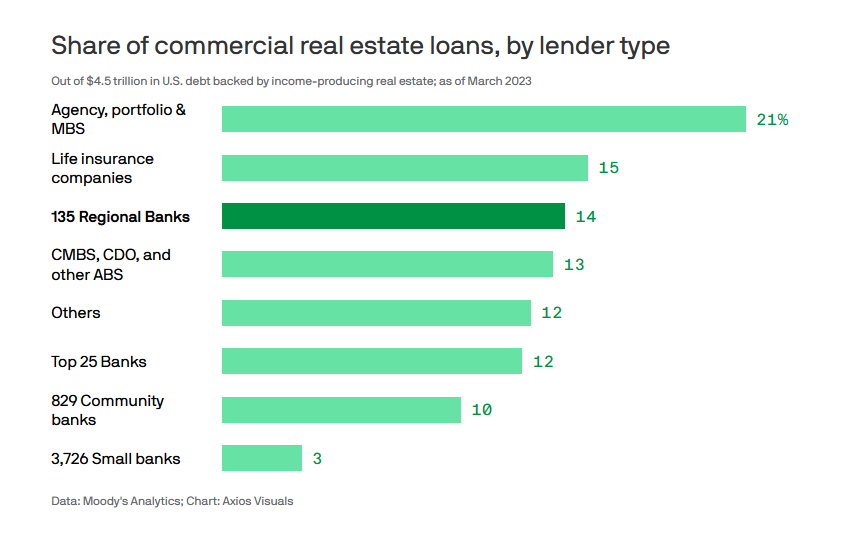
What is scary here, particularly for holders of ‘safe money’ income annuity programs, is that life insurance companies hold a slightly higher percentage of commercial real estate loans as 135 U.S. regional banks in total, together, they hold 29% of all commercial real estate (CRE) loans as of March 2023. If those loans fail, particularly with insurers, their payouts are potentially at severe risk of default also. The small community banks and the top 25 banks hold another 22% of the total amount of CRE loans.
As I think I mentioned last week, the Federal Reserve and the U.S. Treasury Department have pinned themselves, and thus the U.S. economy right into the “coffin corner” with Congress putting the dagger in the back of taxpayers by not having any spending limits or debt ceiling until January of 2025.
If rates rise, the Treasury Department must pay more interest for debt and that increases that spending level as a percentage of all expenditures. It will not be very long before interest payments outweigh defense expenditures, and shortly, it would exceed ALL expenditures that are non-interest rate payments.
Without real revenue growth from things like our natural energy resources to create revenue and jobs, we will have difficulty climbing this spiral forever. As I mentioned last week, if the Saudi Arabians join BRICS, that will deal a blow to the “in-U.S.-dollar” trade of energy commodities, making our currency less desirable for overseas trade, and less desirable to hold U.S. Dollar-denominated DEBT. Borrowers will demand HIGHER returns for Treasury bonds, and the deeper we go into the “coffin corner” until some kind of default or debt jubilee happens. Either way, the value of your assets and your standard of living. It will be a shock perhaps rougher than the UK felt after World War II. Decisions would have to be made to cut or curtail entitlements to insure the defense of this nation. That would also impact Social Security, Medicare, and Medicaid.
I have discussed the effects on consumer inflation should we eventually lose strategic reserve currency status. All the inflation we exported to other nations during our psychotic printing binge will come back to use in higher and much more variable commodity input prices for domestic American manufacturing.
That is where we are that the moment, and perhaps we will know if we have a monthly pivot perhaps to lower equity prices going forward, or whether the party for cheap money lingers on and prices rise until they can’t, at the end of the spending binge, when the lights go out. Every month we get closer to the latter event happening, particularly when spending, printing, and borrowing go without end or even restraint.
I have no idea which way this market or other markets will go, but I think it will be within the ranges I specified over the last three weekend reviews. It could be a 7-handle or a 21-handle. It truly depends on which way things go. If we do hit the 21-handle first though, there will likely be no discernible returns beyond that point for decades perhaps unless there is a major reversion to the mean of equity valuations and until U.S Dollar currency soundness is returned and Congressional spending and debt creation are curbed radically.
That is basically all I have for now. We will see the picture unfold as the week proceeds. I will still be here to analyze MNQM23, MNQU23, and beyond.
Have a great week everyone.

