

There will be no video today. Some of you will jeer but most may actually cheer that decision. They will return again soon.
You have already seen the bullish case for MNQU23 last week. It was quick and easy to do and because of network issues, I could not write a full post. All of that seems to have faded in the background.
I want to show you what might be a cautionary tale at the weekly and monthly levels. Does it negate the entire rally and its continuation? Of course, it does NOT!
It does, however if it follows through, provide perhaps a technical indicator that we may indicate that growth stocks may have hit a roadblock for the drive by your casino operators (the U.S. Federal Reserve). A lot depends on future Fed action and economic activity, but there are some foundational economic issues of valuation that must soon be faced by every part of the securities, commodity, real estate, and business economy generally.
What potentially looks shaky technically?
Let’s look at a monthly chart of MNQU23.
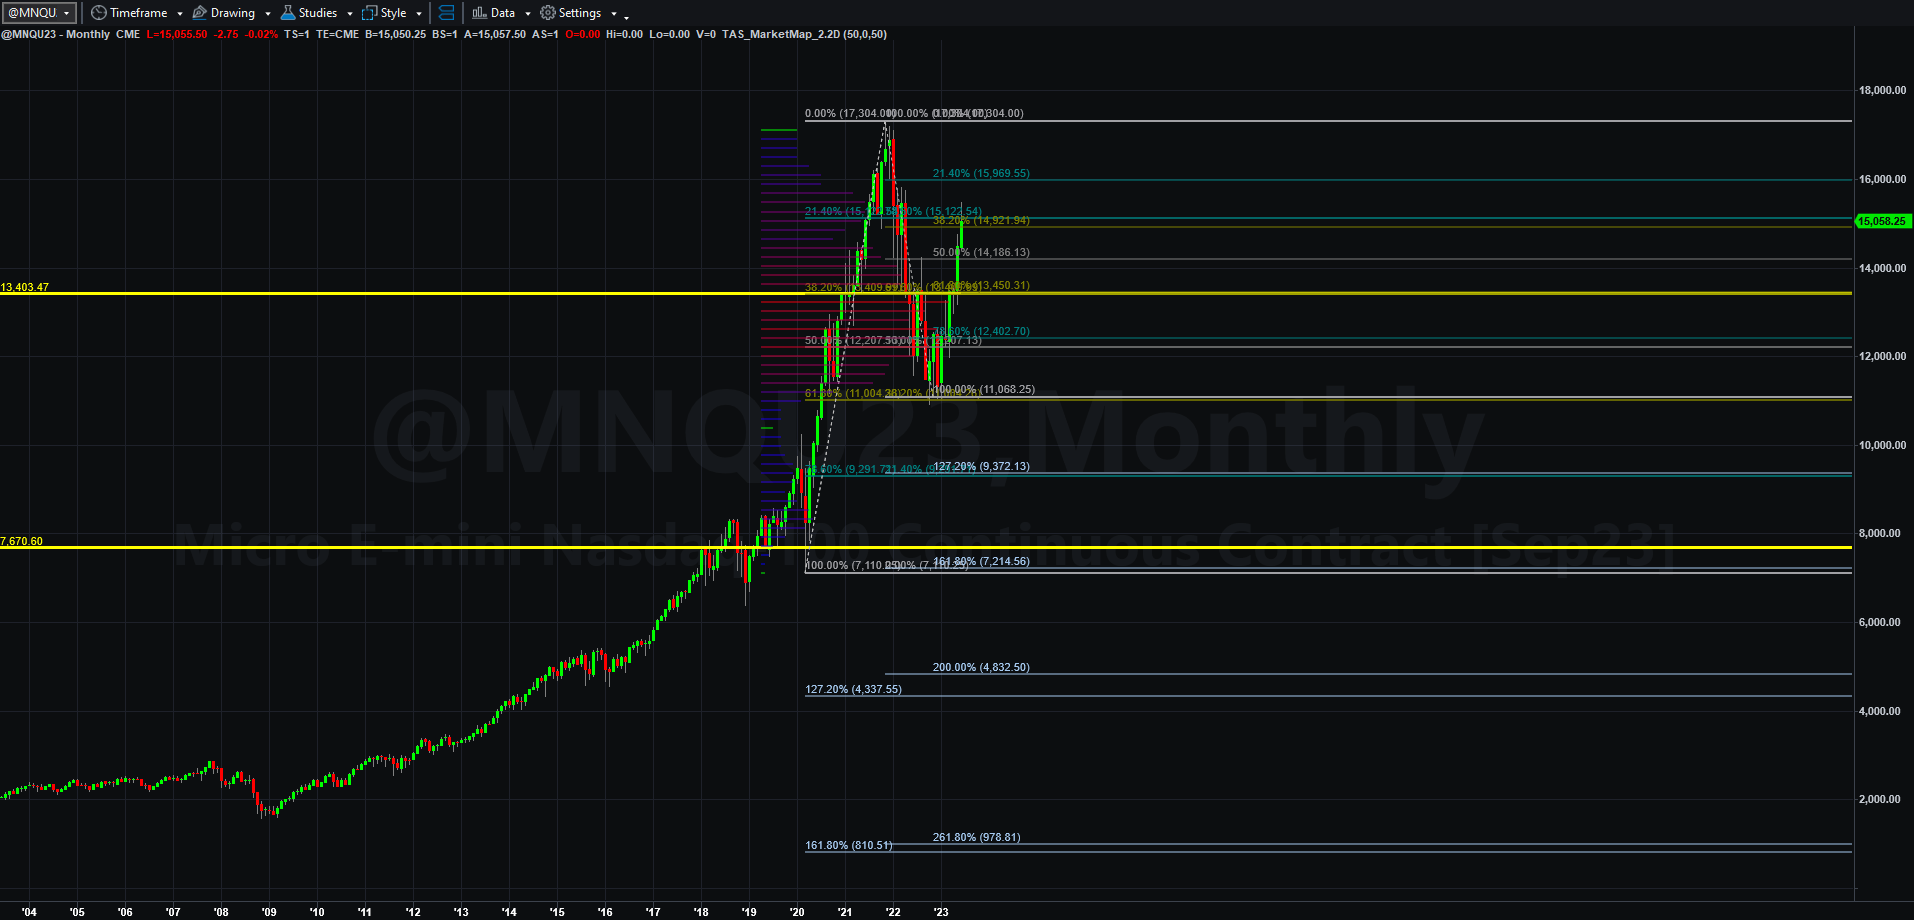
On the monthly, there is a potential pivot point, which is the high of the June bar which is 15475.40 as you can see if you expand the chart above. Why do I say it’s a potential pivot? Simple, because for now, it is an actual pivot on the weekly chart shown below.
Here’s the weekly chart of MNQU23:
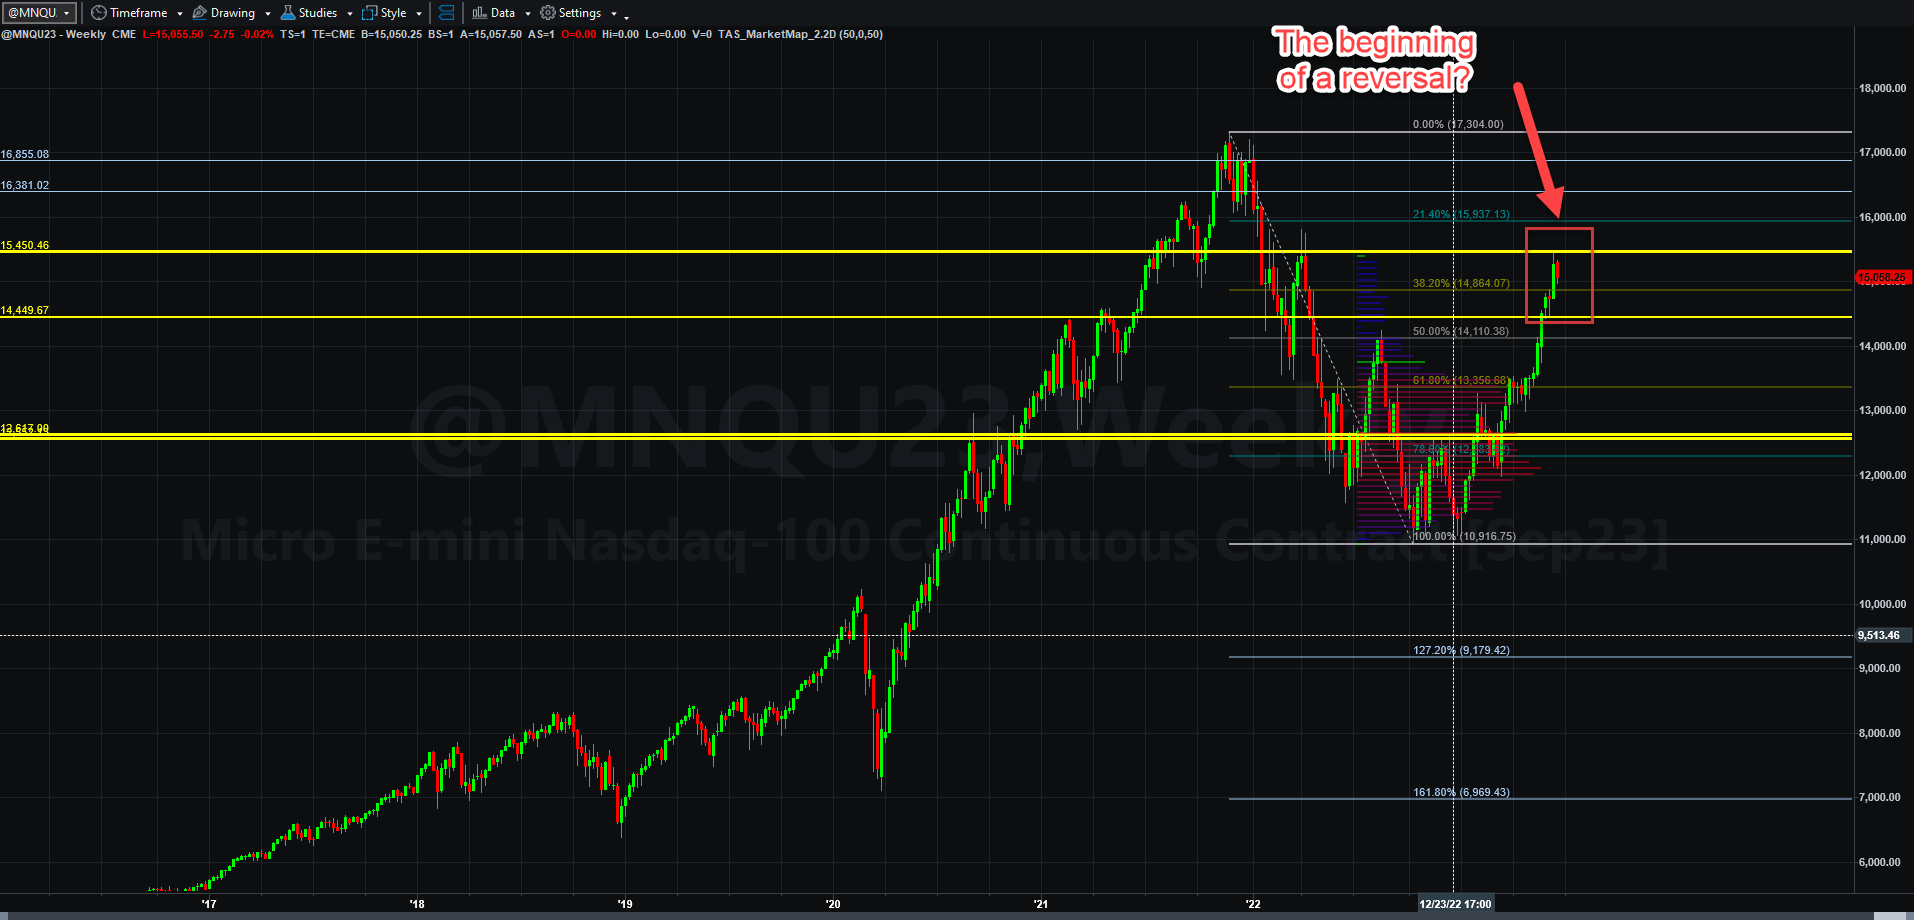
You can actually see this past week’s bearish bar that closed at a lower high than the week before. The other thing you see here is that there is a weekly VWAP line very near that previous higher high pivot, which could mean solid resistance to any further rally about what is almost a perfect 61.8% retracement of that last large weekly swing.
If that pivot were to hold, and there was a second AB=CD selloff symmetrical with the first that occurred after November of 2021, one would see this as the potential target, from the monthly chart:
Here is the monthly MQNU23 chart with targets and VWAP lines included:
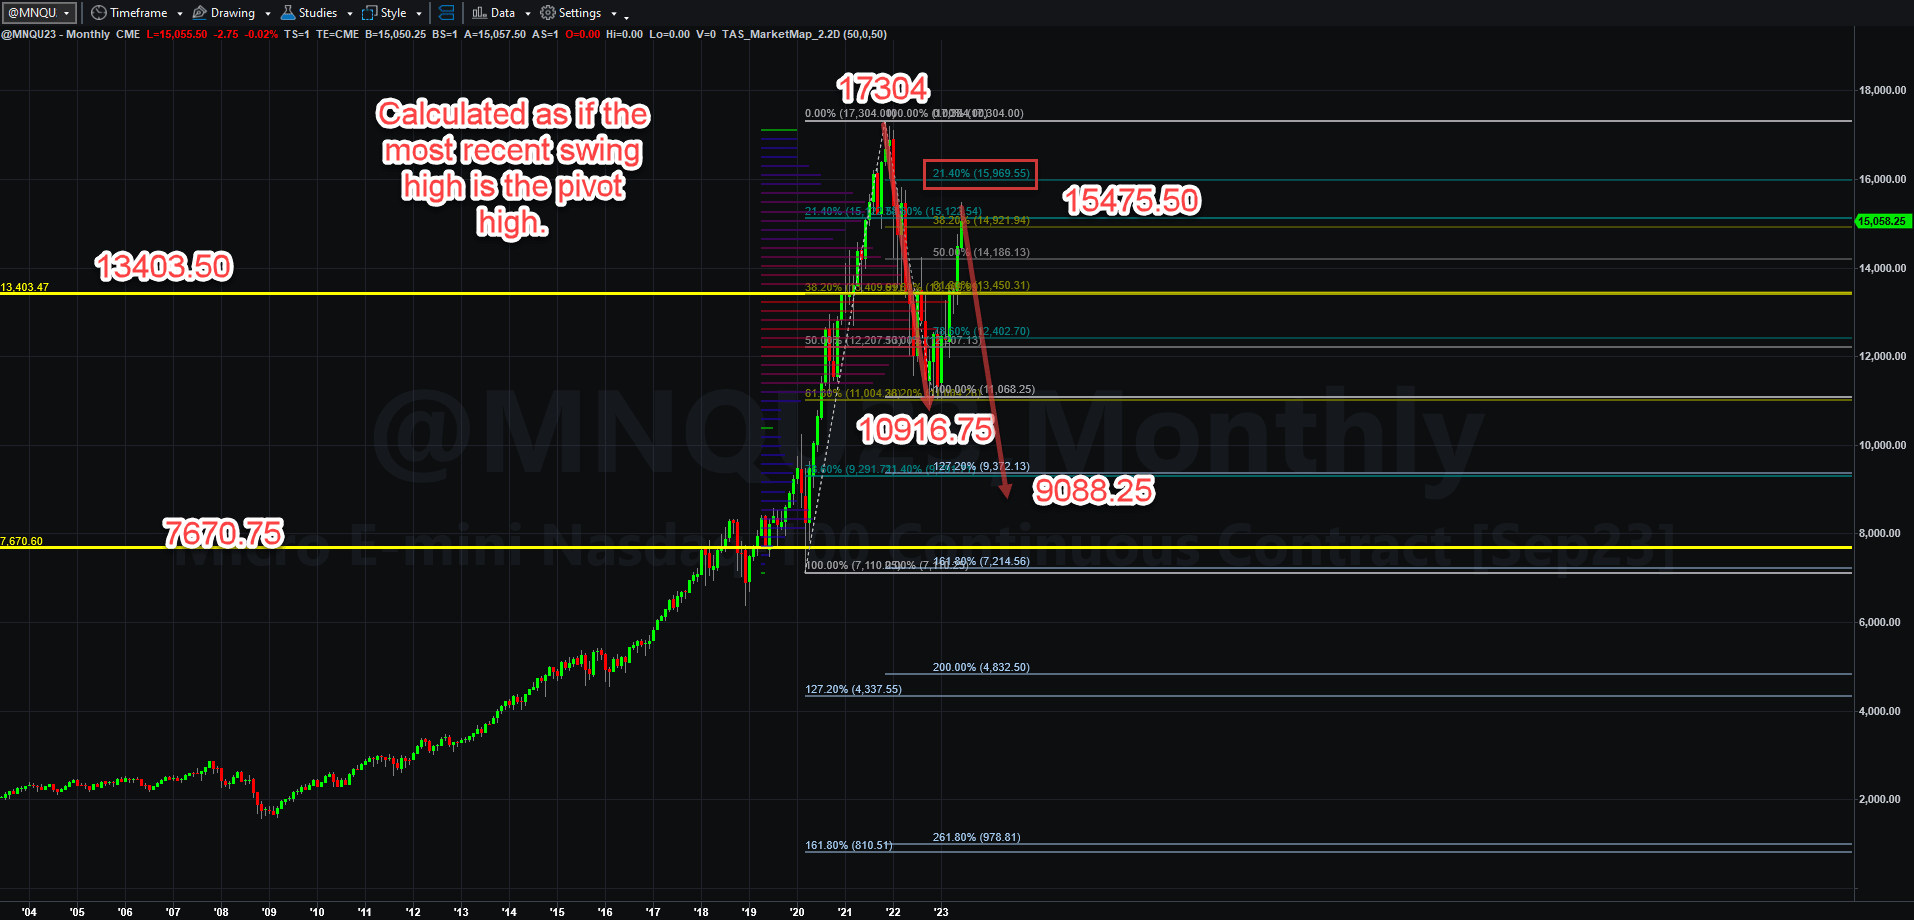
If that pivot stands and a symmetrical correction happens, then the target is 9088.25 (back to that former resistance level from February 2020).
Why Be Bearish?
I am not a perma-bear…and I won’t use the old slogan I used in my radio days (some of you know what that is and are sick of it). I am basically agnostic in terms of direction for this market. What I AM concerned about is what the value of earnings will be for stocks in the future, and why an increasing rate environment may just force the issue. That would be something ultimately favorable for young investors if the fascists in this government do not overrule earnings for ESG scores, something I can discuss at another time and that has not been resolved as yet.
Look at this chart from Bloomberg and the Financial Times:
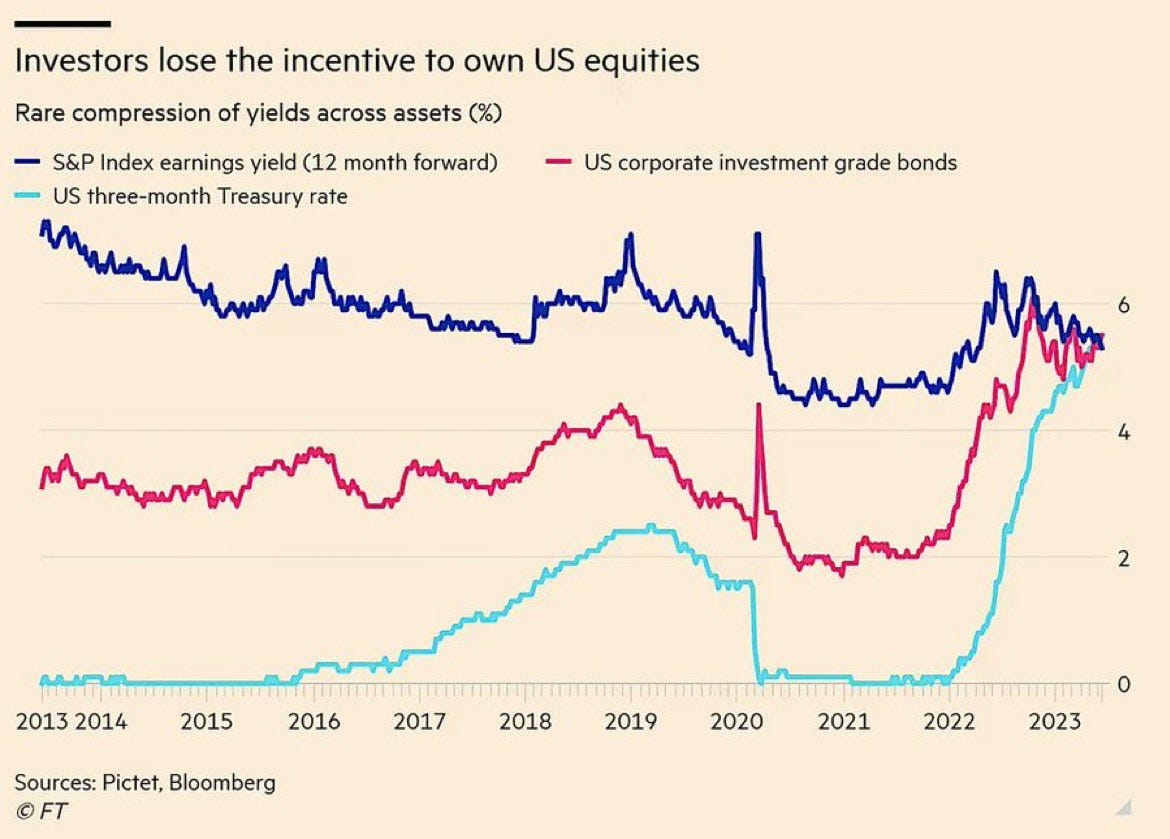
What we are seeing in real-time is a convergence of asset returns across all asset classes, index earnings yields, corporate bond yields, and even 3-month treasury yields. That means that if rates continue to climb and the U.S. economy slows dramatically, you will likely see equity prices fall to meet the return of higher fixed-rate yield investments. Remember too that if dividend payouts are threatened by a slowdown and get cut as they did in 2008, the ability of S&P 500 total earnings yield probably gets crippled for an extended time in its race to outpace fixed income yields of corporate or government bonds.
There are certainly reasons for bulls to get excited too, as Carley Garner shows in her most recent Decarley Trading substack.
The consensus of traders may well indicate that the massive short positions in ES (and to a similar degree NQ) may have been unwound, and more money could indeed come rushing in, as the U.S. Dollar seems to be showing strength internationally once again. To quote her Substack directly:
“The COT might show that roughly 40% of the shorts have been squeezed out.
We won't know until Friday when the COT Report is released by the CFTC, but we have a feeling that almost half of the historic net short position being held in the E-mini S&P 500 futures market was unwound on last week's highs. As a reminder, the report data is collected at the close of Tuesday's trade and released on Friday. So even the figures reported each Friday lag a few days. Nevertheless, we will soon know what the market composition is. If we are right, a good portion of the short squeeze risk has been alleviated and that might allow a healthy correction to ensue.
The ES bears will want to see a close below 4400; this is what it will take for prices to fall back within the previous trading range (negate the recent breakout). A close above this level on Friday would be highly bullish. Let's see what happens.”
Even with that being said, the idea that tightening is over is probably not the best guess in the world to make when NVDA is priced at nearly 40 times earnings, meaning you will not recover your full investment until 4 decades from now. As a cash-on-cash real estate investor, I would not buy anything over 70% loan-to-value, meaning I built in a 30% return once a flip or lease/option was created. Taking a 40-year bet on a residual piece of paper in a business is more of a stretch on any kind of rational time horizon.
Even Ed Yardeni feels the hate of this rally but still thinks there is strength.
There’s Lots of Crazy Stuff Going On To Be Concerned About
So what’s the big deal about rate increases? Well, in and of themselves, it’s not a total disaster, though rapid changes in rates can choke off an economy.
What is really scary is shown in this chart from Mises dot org, and this accompanying article.
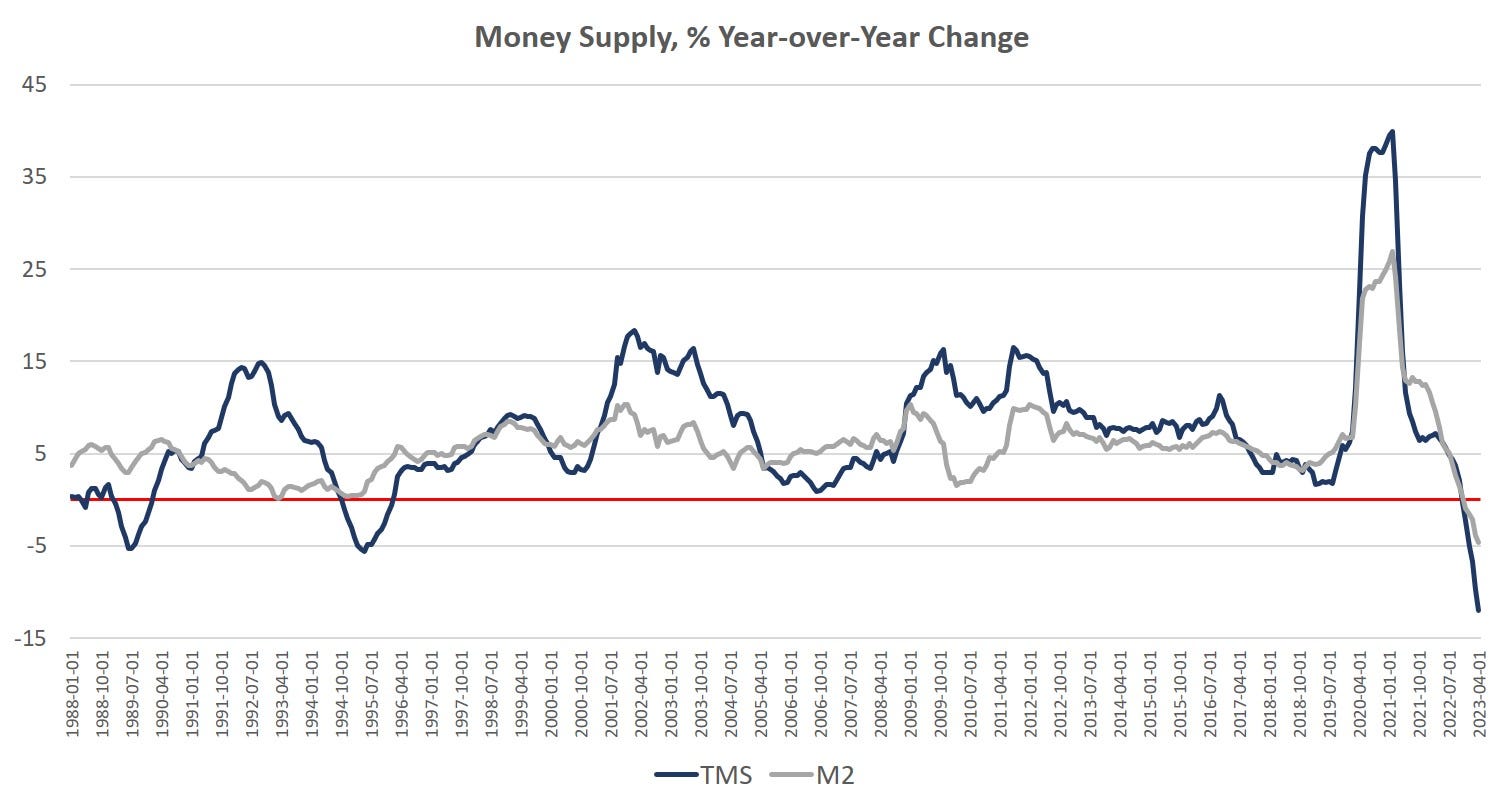
The year-over-year money supply has dropped precipitously in the last few months, something we have not seen the level of since the Great Depression in the USA. (Data from 223 years of American history is shown in the linked FRED charts. Bankruptcy filings were up 23% from a year earlier in May 2023. LEIs are also slowing and temporary jobs are fading, all signs of a coming recession.
The other scary thing is that the Federal Reserve owned 2.6 trillion U.S dollars of mortgage securities in April of 2023, according to May - June 2023 The Austrian article “The Fed’s Cincinnatian Problem”. That was more than the entire Fed balance sheet in 2008! Not only that, but that same article shows that the Federal Reserve took a 408 billion U.S. dollar mark-to-market LOSS on that portfolio in 2022 ALONE. How does that make you feel about U.S. regional bank stability? To use economist language, that scares the bejeezus out of me.
The expansion of the money supply has been insane, and the asset bubbles created will at some point have to be dealt with. It is not possible to rescue entire segments of the economy with essentially worthless currency (particularly after the Biden Administration destroyed the petrodollar through the bungling of Saudi Arabia negotiations over oil production.
As momentum among the BRICS nations to create a commodity-market-basket-based currency continues to make progress, the prospect of de-dollarization gets closer and closer. The U.S. Treasury, U.S. Congress, and U.S. Federal Reserve need to fully realize that when that condition accelerates, the ability to solve problems by printing money into infinite numbers will end, as markets will want higher returns for the risk of increasing debt, the increasing risk of complete insolvency, and lower money circulation. That will very shortly put interest payments at the top of the U.S. Congress’ expenditure items, and the ultimate bankruptcy of the United States of America at the Federal level will indeed be nigh.
And just at the ground level, if you look at the 1980 calculation for consumer inflation delta, year-over-year, you are still in double-digit territory as calculated by shadowstats.com. In May 2023, that number was calculated at 11.93%.
Think that number is bogus? Think again, even leftist-leaning Yahoo Finance admits that 10%-plus food inflation is going to be here for the time being. We also know that the Saudi oil production cuts have not yet filtered through the economy. As the U.S. strategic oil reserve circles the drain to zero by Executive Department dictates, gasoline prices will not remain still as we continue to limit production and even buy diesel oil from foreign entities including Russia as America’s refining capacity stands still, unable to grow once again via government interference. Even falling crude oil prices will not stop price rises in industrial fuels and that will present a challenge to American industry going forward.
Even though many have stated of late that Fed Chairman Jerome Powell has lightened up on this hawkish stance on rate policy, I still believe he will raise rates going forward, particularly if consumer inflation does not cool off. the American Uniparty Congress will have to make tough decisions regarding budget discipline and spending reduction, or the American economic train will eventually fall off the cliff.
Conclusion (?)
I will try to increase the detail level on economic valuations of equities, but I think the case is clear that some kind of mean-reversion for equity prices is on the way, given the way risk is allowed to be priced in the current environment. I said years ago that the denouement of the “free-money” casino would end at the Fed funds rate of around 5%. My “Nostradumba%^” prediction seems to have come true, but only time will tell.
I think anyone who is rational will look at their portfolios and clear the decks of stocks that cannot justify their value in an increasing rate environment and in a historically overpriced price/sales and price/earnings environment. If somehow fiscal and monetary discipline can fight off the cancer of ESG mentality, and we can return shareholder value to investors and not ideological brownie points to business oligarchs, we might just have a chance to buy truly cheap equities to hold onto without the twisted and often complex hedge strategies designed to fend off the almost every-decade finance Armeggedons.
Value can work if free markets are allowed to exist. We need to get back to that point as soon as possible. Until then, I think everyone should hedge their assets and readjust their portfolios to protect their wealth, given what I have presented here today.
Have a great week next week everyone!