

I posted a video despite my strong aversion to doing so. It paints the same picture, save that it looks like last week could be the portal for a reversal if looked at on a weekly ( 2:02 ) or a daily ( 6:20 ) basis. Before imputing bullish euphoria or bearish bipolar reflex (I made that up simply for the alliteration), I think it is important to realize there are factors pulling and pushing this market, the S&P 500, and the American equity markets. I am going to expand the discussion a little from last week.
This post is going to be full of rich media, and despite your resistance to doing so over the few days, I would suggest you read and watch it.
I do not want you to simply agree with me, but I want you to inform yourself and think about it. You will have accomplished more by doing that than almost a century’s worth of politicians have :) .
If you are to believe the retired-but-still-acting-like-wirehouse-brokers like John Mauldin (who despite that I still admire some of his research), you believe that U.S. economic activity is in “muddled optimism”. If you recall, he basically called the “lost decade” of stock returns in the 2000-2010 era the “muddle-through” economy. He might not get a Pulitzer Prize for literature, but he thinks that inflation is cooling and the earnings seem reasonable for the insanity we have lived through since Q1 2020. The thing he is not as pressing about is that almost all of it is government-created and with the most recent Congressional budget, fomented.
The site Game of Trades, a macro-technical analysis website, does a great job of showing the technical factors that should lead to a fairly strong continuation of the rally we have had thus far. The two things that bother me most about this are that the price/earnings ratio (PEs) is extended to 25. That is something that is incredibly rare. It leads me to not buy the head-fake of “continued rally” much like I shouldn’t have in 1987, when Norman Fosbeck, himself a quantitative technical analyst) was one of the very few, including my mentor Larry Pesavento and Paul Tudor Jones, who readily called correctly for the U.S. equity markets to take a beating in the fall in early August of 1987. The latter two men I mention made fortunes in that crash. As they say in South Carolina, I got my butt whooped as I was heavily invested in technology at the time. The other thing that is a bit crazy is that the Fed is forecasting a fairly sharp rise in unemployment and STILL not calling for a recession. His contention is also that inflation peaks are often followed when they cool off by massive stock market rallies.
This year, however, is NOT 1987 or 2003, or even 2008. There are macro factors that are not purely cyclical in 2023. Let’s look at the major ones I picked out today. There are more, but these I can handle in relatively short order.
Is Inflation Really Cooling?
Inflation could be cooling in energy (but I will deal with that at another time), but in grocery store shelves and produce aisles, I would have to say NO.
The recent drought has caused problems for items like corn and soybeans, which keeps cereals and other staples expensive ( as if they are not insanely costly already). Household goods and processed foods are running at least low double-digit percentage gains, and even USDA forecast earlier this year food inflation across the board to continue on pace with nearly 20% per annum price increases in some cases. Tradingeconomics dot com, produced an article that shows current food inflation of 6.7%. It may be slowing but it is still running at triple the nominal rate we have seen from 2002 to 2019 inclusive.
For the middle class, and particularly with coming restrictions on nitrogen fertilizer which will reduce food production yields, the inflation story is NOT DEAD by any means yet.
What Other Pressures Are There To A Market Rally?
We have already talked about inflation in consumer staples. What about the deterioration of the currency adding to the problem? Look at this:
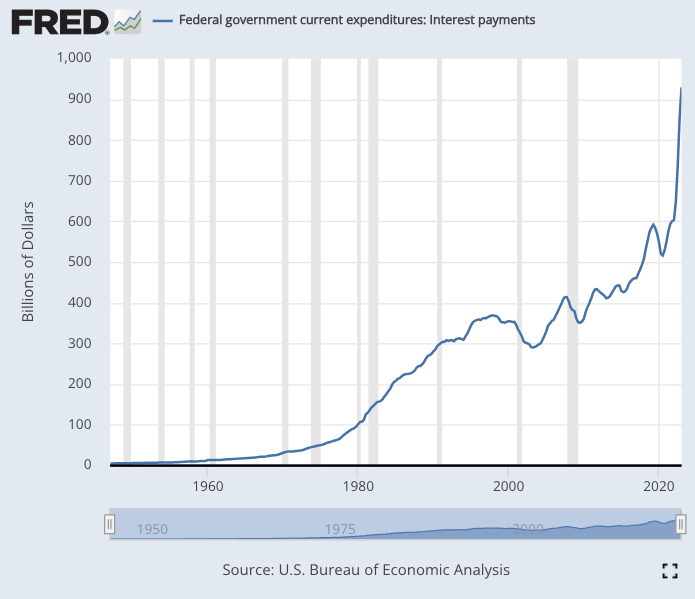
As far as the taxpayer and the investor is concerned, the asymptotic rise in interest payments will only continue as the Fed tightens and continues to print and borrow. That will affect citizens and businesses as well, as they all must pay the burden of indebtedness.
The other scary thing is the rapid decrease in household net worth, that is sinking almost as fast as it did during the “great recession” of 2008 (also government-fomented):
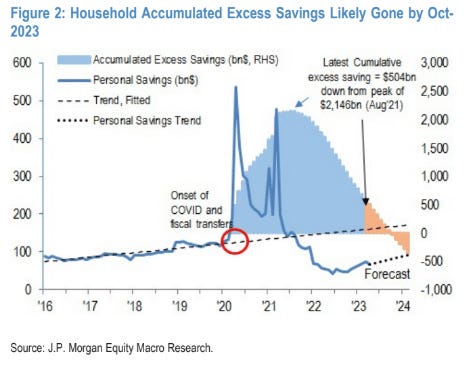
A slightly better view of that can be seen here from the Fed:
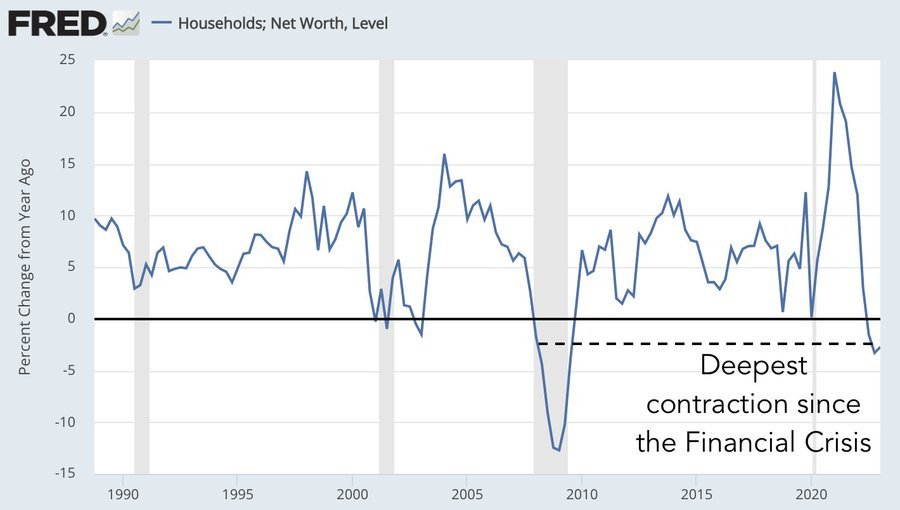
Consumers could become tighter than ticks with their money and that lack of demand will slow the economy down for a while. When you also see the printing presses whirr and the spending continue unabated which it will until at least January 2025, one has to wonder how economic expansion can sustain itself in terms of earnings and stock valuations as described in that Game Of Trades video above.
The other issue that has once again reared its ugly head is the fact that Russia has confirmed its intent to create a gold-backed (and likely also commodity-backed) currency for the BRICS members on Friday. De-dollarization over time will become a reality. The thing that might save it is China’s economic and currency woes, but at some point soon, given Saudi Arabia’s expressed desire to sell crude oil in something other than the U.S. Dollar will likely come to pass, particularly if the American Uniparty continues to hold power in the Executive Branch after January 2025. That reversal would make it increasingly difficult for the USA to continue to print money flagrantly without accelerating inflation into republic-suicide territory.
What else could go wrong? Well, you could try America fomenting a kinetic war against Russia using cluster bombe weapons used for “war crimes”, as Joe Biden called them. That sort of thing could lead to an expanding thermonuclear war as well.
Supporting neo-Nazi leaders, people we fought against in World War II, is not a sane prospect, particularly when deploying cluster bombs as are. Yet, that is what Uniparty acolytes like Joe Biden, Mike Pence, Nikki Haley, and Lindsay Graham wholeheartedly support. We are seriously escalating a regional conflict we have no business being involved in. It is equally daunting to me to think that Nikki Haley thinks supporting Ukraine supports democracy when Ukraine’s leader cancels elections until after the war is over. The irony and insanity in holding such a position are dripping. That stance could do more than just destroy our economy.
Final Statement
I am going to leave the discussion here for now. We clearly have the antecedents of a continued rally IF the only thing that matters is that inflation is cooling and that we see large rallies in stocks after a peak in inflation. For me, the problem is that with all the insane Fed policies pushing regional banks into a corner and driving Federal debt continuingly out of control, the inflation component is STILL there and isn’t going away, in my opinion. I didn’t even discuss the fact that consumer credit card debt is at all-time highs and that people are using them for necessities and not just for large-ticket items. I mentioned nothing about manufacturing and the issues with semiconductors we have currently (something I have mentioned in the daily commentary).
Because I can and DO go long and short as I see fit, I don’t have to be worried about being locked into long-only positions that can be torpedoed if things get crazy with the economy or with government action. Anyone who is needs to realize that at some point, the joy ride that has existed since 2008-2009 and accelerated by nearly endless quantitative easing will have to end at some point as wanton and profligate spending cannot last forever. Keep your eyes open and be aware of the dangers, and they are many and they are growing.
That is it for me this afternoon. I will be writing again tomorrow!
If you like this, hit the like button! Thanks again to all you new and current subscribers. As time goes forward, I will do all I can to improve this Substack.

