

The above video looks at how the confluences of price/volume interactions, Fibonacci patterns, and volume profile will affect either side (bullish or bearish) in the days and perhaps weeks ahead.
What people need to become painfully aware of (particularly if you are a long-only holder of assets, whether they be real estate bonds, equities, and even cryptocurrencies) is that there are likely the dual effects of a hyperinflationary and stagflationary economy and an overt attempt by those in charge of the Federal government to cripple or at least throttle the economy for their own political gain.
Jim Cramer may still think this is a strong economy, but if he were fully aware and were not a partisan, he would understand what is happening. I am a libertarian or “conservaterian”, but I work with factual presentations and not memes. I do not support the current two-consonant (formerly two-party) political system. Both of them are self-serving and care nothing about the citizens they represent other than to control them in any and every way possible. I try to live within the realm of reality, as that is all I can deal with hour-by-hour and day-by-day.
The Pain Of The Current Economy That Could Effect Corporate Earnings Eventually
The reality at the moment is quite sobering, and it will affect every asset class available to any investor of any size. I will now do my best to explain why using the data I have before me. Let’s get going.
Here are some facts that one can glean from my data:
On the basis of economic growth, the United States economy is in a recession currently. Why? It is recessionary because it has suffered two consecutive quarters of negative growth. That is a textbook definition. Handwaving is not included in that definition.
There may be even more coming. Maersk has stated that shipping hit a wall in terms of growth in July 2022 as orders have dried up. FedEx is also now seeing a global recession ahead.
While recent consumer confidence is still slightly bullish, it comes at a great cost to the American consumer in terms of credit. People are spending money on necessities and not luxuries, and they are putting it all on credit cards.
Americans have taken the largest hit ever on savings as a result of the expanding cost of living in the second quarter 2022. It hit 6.1 trillion dollars.
A Freddie Mac survey “found that nearly 1 in 5 renters whose rental costs rose believe they are likely to miss a payment. Only a third of renters who earned pay raises in the past 12 months said their new incomes will cover their new rent.”
20 million American households are also behind on utility payments currently. People are not able to pay for necessities as they once could. It’s likely to get worse as the Biden administration continues to throttle the use of any hydrocarbons ( natural gas or oil ) to be used for basic heating. They’re following the same dangerous path that Germany is currently. People there are scrambling for firewood.
Because the so-called “Inflation Protection Act” gives the EPA authority to regulate methane and to limit the use of nitrogen-based fertilizers, critical factors in high-yield agriculture. It is also trying to enforce low-yield farming techniques which could result in food shortages as very likely will occur in the Netherlands, where cattle farmers are being forced to limit dairy and meat production. The science community seems excited about it, but consumers should not be. That will only limit supplies and drive prices higher.
Fertilizer prices and fuel prices are all on the rise because of new regulations and restrictions levied on the chemical and refining industries. With the Biden administration’s goal of “ending the fossil fuel industry” this administration and Congress may add windfall profits taxes on these industries. Those costs will be paid for my the industries, the farmers, and eventually by the American citizens in higher consumer prices. Taxes are not paid by corporations, folks, they are PAID BY YOU. They are a tax ON YOU.
Implied inflation By Government Overreach
We have heard all the horse manure from our elites about how “transitory” inflation is and how the economy is robust. As one can see from the data above, we are not in great shape at the moment. It can get far worse if prices escalate and supply chains are manipulated into emptiness.
Consider this:
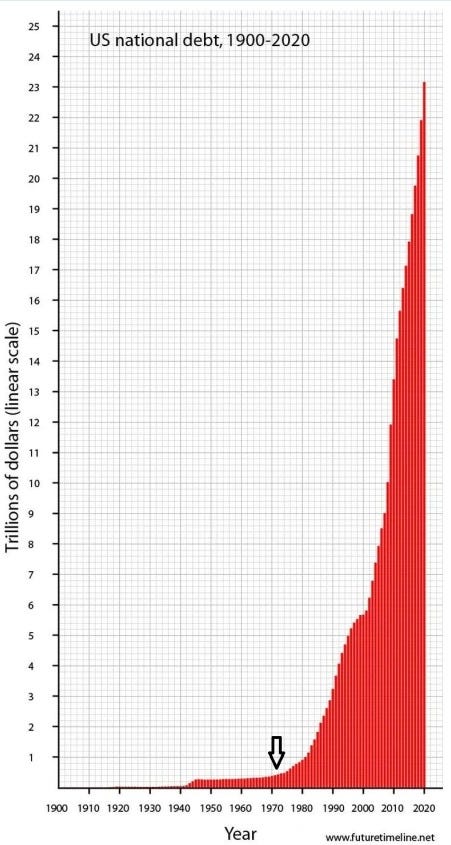
After the USA went off the gold standard in 1971, our national debt exploded. It really launched during the beginning of low-yield bond rates, which made it easy for banks and crony corporations to leverage the economy for their own wealth, and it truly ran off the rails during Clinton’s administration and Bush, Obama, and even Trump and cheap money meant the government could borrow money and banks and institutions could deploy low yield money in risky assets, while savers’ wealth collapsed. When the so-called “Great Recession” hit, rates were driven to zero, after inflation, and borrowing could continue as long as money could be printed to support it. We printed more money in the last 2 years than in the other entire history of the republic combined.
We were told that inflation was always held to a target of 2%, but what was that target really? Before 1983, all volatile components of inflation were included in the Consumer Price Index (CPI) calculation. Pull that out, and then “everything was fine.” In reality, as I have graphed with data from shadowstats.com, the real inflation rate was much higher. Take a look.
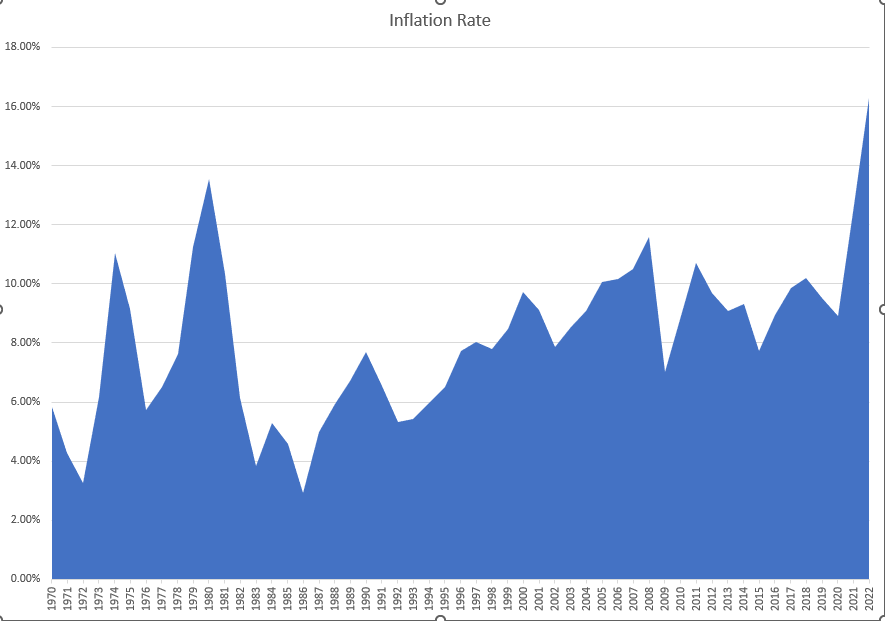
That is what the data looks like if it were calculated the same way it was before the CPI data was changed in 1983. From 1970 through August of 2022, that data averaged 8.11% per year. From 2000-2010, it averaged 9.28%, and from 2011-2022, it averaged 8.89%
Look at the Fed Funds rate over that same time.
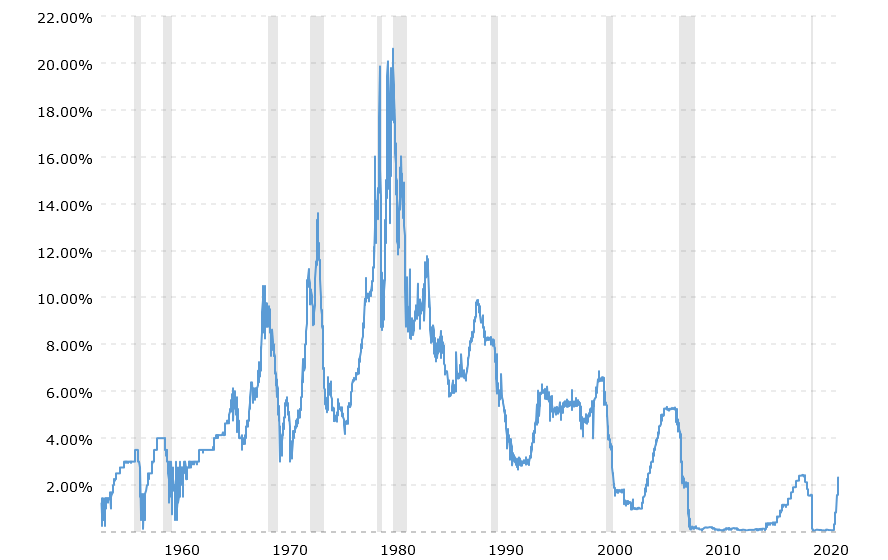
You don’t have to be a rocket scientist or an economist to figure this out.
Let’s put it this way, do you see the Fed funds rate reflect the so-called risk-free rate of return being above the average inflation rate of 8.11% after 1980? You get bonus points if you said NO.
The Federal Policy Institute calculates that average annual wages have increased on a nominal basis by 5.2% per year from 2007 to 2022. Using the Shadowstats calculations, inflation over that period was 7.74 percent, so the nominal wage earner lost 2.0% per year to inflation. That number can accumulate quickly over time.
What is worse is that Congress spends as the Federal Reserve continues to print money, claiming it is spending more. It is spending money it does NOT HAVE. Estimates are that 3.9 million people have crossed America’s southern borders in 21 months, most of which are being paid benefits with money Congress does not have. If inflation is truly now 16.3%, it will take a massive amount of rate increases AND a complete cessation of spending to stop it.
What equity investors need to realize is that the Fed could be hopelessly behind in adjusting interest rates to the true inflation rate. Fed funds rates were 20.61% at the peak of the crisis on June 15, 1981, and inflation that was created behind it was 10.33% (down from the peak inflation of 13.55% in 1980, then the Fed funds rate was raised over the inflation rate of roughly 10.28%. If the true inflation rate is 16.3, then the Fed funds rate would need to be nearly 26.58% (let’s just call it 26.5%). That is probably what it might take to crush the current inflation. That would also crush the equity markets, the bond market, and most real estate markets.
There are two problems with this.
The United States is no longer a deep and wide manufacturer of goods. Private businesses cannot absorb the excess liquidity in the economy to produce and export goods the way they once did. Its key source of export, ENERGY, has been knee-caped by what I call the “enviro-fascists” in power currently.
The other problem we have is the combined “print and spend” mechanism that has made us the greatest debtor nation in human history (that we know of). The combined “Uniparty”, comprised of both mainstream political factions (though I call them co-conspirators in crony capitalism) only wants to run the printing presses and continue promising more entitlements to citizens to buy loyalty. THAT MUST STOP. We have printed more money in two years than in the rest of the history of the republic combined. That is IN NO WAY SUSTAINABLE. It is the surest ticket to Venezuela or Zimbabwe that can exist anywhere else.
Conclusion
All I can do is project what prices can do in a “near-field” environment based on what I know from H.M. Gartley, my mentor Larry Pesavento, and volume profile analysis that I have learned from Brian Shannon and others.
Enough rambling. The risks to equity markets are huge, but sanity could be restored if these poltroons are removed from Congress in November 2022, ready to fight this Administration with logic and economics knowledge. What are the chances of that? We will simply have to wait and see.
Gotta get other things done. As always, THANK YOU FOR SUPPORTING THIS BLOG!

