

The prognosis has not really changed. If MNQZ22 breaks below 10139, I think the bears will continue pressing closer to a symmetry target of 8087.50, assuming that there are not levels of support around the 9800 level or lower as discussed before. Those support levels could create opportunities if there is (God forbid) a Fed pivot, something even Jerome Powell now says is unlikely because of the strength of inflationary pressures caused by the admitted printing of “digital money”.
Please watch the video for that analysis.
Let’s dig deeper into why we might expect lower equity prices ahead for tech stocks and for other sectors. Remember, I will trade in any direction, up or down, that matches the combined factors of my trade plan for volume, price and volume momentum, and Fibonacci pattern or extension, based on what I see on the chart. Regardless of that, I still think there are economic factors that will drive prices lower as we enter 2023.
Energy Supply Shortages, Particularly Diesel Oil
President Biden rather insanely called for oil companies to drill more domestically and to refine crude oil to increase supplies. Why is that insane? It is insane because he signed executive orders reducing oil production by 2.5 million barrels a day domestically. Refiners because of regulations put on the oil industry from the Clean Air Act of 1970 forward to state regulations and additions to laws created by the unconstitutional Environmental Protection Agency. No new refining capacity has been brought online since 1979, and refining capacity has been cut by the Biden Administration, which has shut down at least 7 refiners. Active Refiners are running above 90% capacity currently, and it is nearly maintenance season when refinery equipment needs cleaning and proper mechanical maintenance to produce more gasoline, diesel oil, and other refined hydrocarbon products. Refined product capacity has been cut by 1 million barrels per day in this country.
With our nation seemingly on a war footing on multiple fronts, our strategic petroleum reserve could dwindle to zero by year-end. This seems to have been a political move by the Biden administration to provide a faux reduction in gasoline prices while destroying domestic emergency supplies.
All the while, as major oil companies fight back, Biden threatened to bring windfall taxes (another brilliant idea, since CONSUMERS PAY ALL CORPORATE TAXES AT THE PUMP or anywhere else they buy products at retail. ) As mentioned in the first linked article in this paragraph, Biden may, in the end, take control of refining assets via an FDR-era law known as the Defense Recovery Act. That is basically how Hugo Chavez took over the energy industry in Venezuela and began the collapse of Venezuela’s economy. The key point is, it would satisfy Biden and the Uniparty (the mainstreams of both Republican and Democrat Parties) to no end to nationalize all energy assets. Remember that most of the growth in GDP in the USA comes from mining, refining, and exploration of energy.
And I haven’t even mentioned diesel oil shortages yet! This article explains why we have not kept up with diesel oil production (much of which is government created, via refining shutdowns, but is made worse by the refinery maintenance schedules I mentioned earlier). Mansfield Energy issued a warning about 10 days ago that diesel fuel would begin to run out in the Northeastern US and the Southeastern USA in roughly 10 to 20 days. That includes my home state of South Carolina. This shortage will begin to spread nationwide as 2022 ends and 2023 begins. That would mean transporting everything from food to gasoline will be more expensive to buy from transportation costs and that covers almost any product that consumers or even industrial customers buy. That does not bode well for the improved profitability of industrial companies in 2023. I don’t think that will help stock prices either. More people than ever are using delivery services as they can longer afford to drive. This will not help things much as fuel prices rise.
Interest Rates and Currency Values
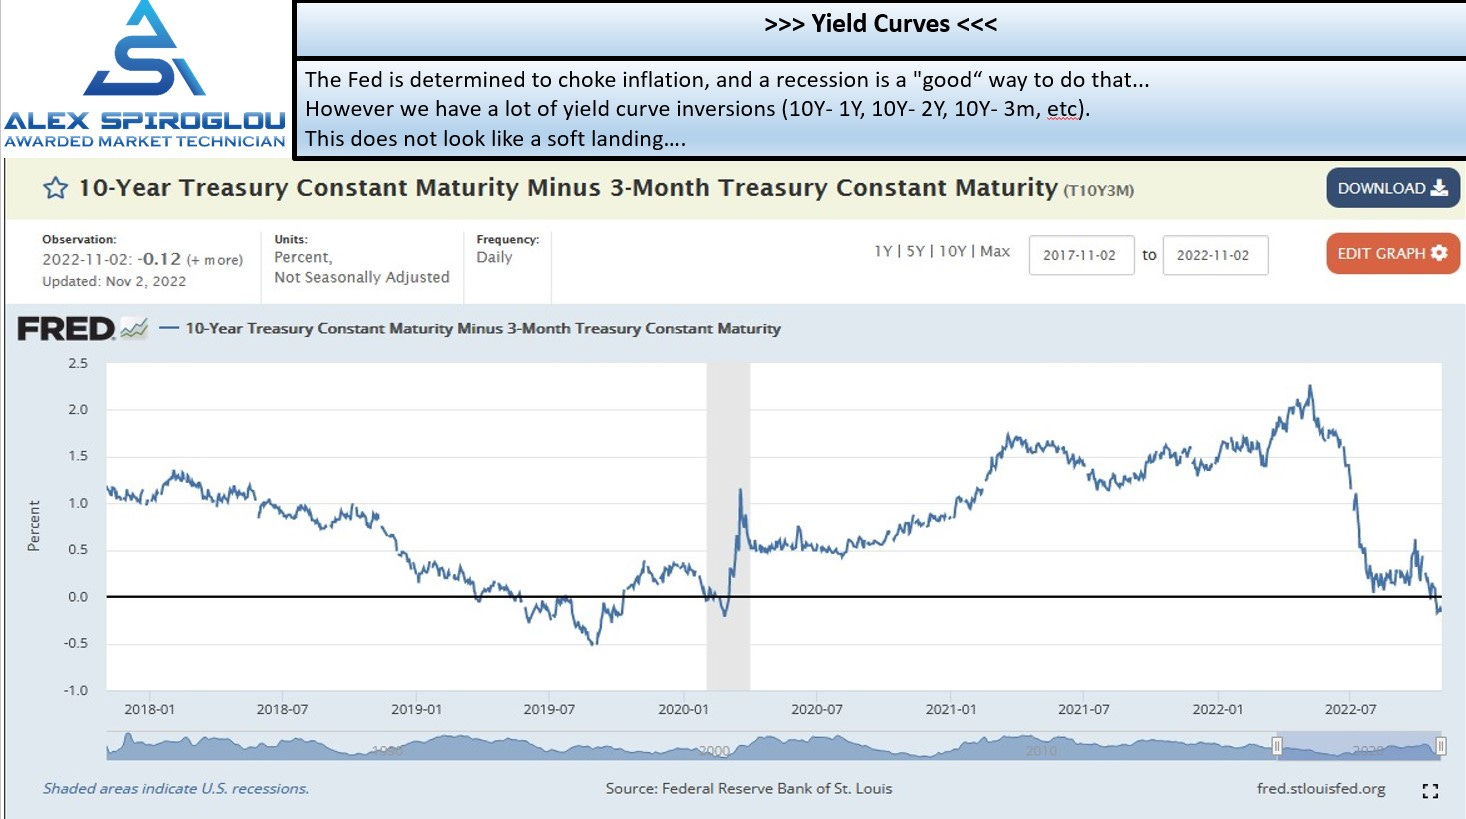
Given what is happening to prices, US interest rates are being forced to rise as Jerome Powell has stated, and a soft landing is likely not possible for the economy. He has even admitted that the printing of money was the true cause of it. Funny how leftists finally abandon modern monetary theory after it destroys economies, isn’t it?
As Alex Spiroglou’s chart suggests, the inversion of the yield curve gets worse. The Federal Reserve does seem farther behind the curve, as I have discussed many times here, and rates will continue to skyrocket.
As rates rise, of course, the US dollar becomes stronger. What does that mean for the Euro? Take a look at this chart of Euro futures for December 2022.
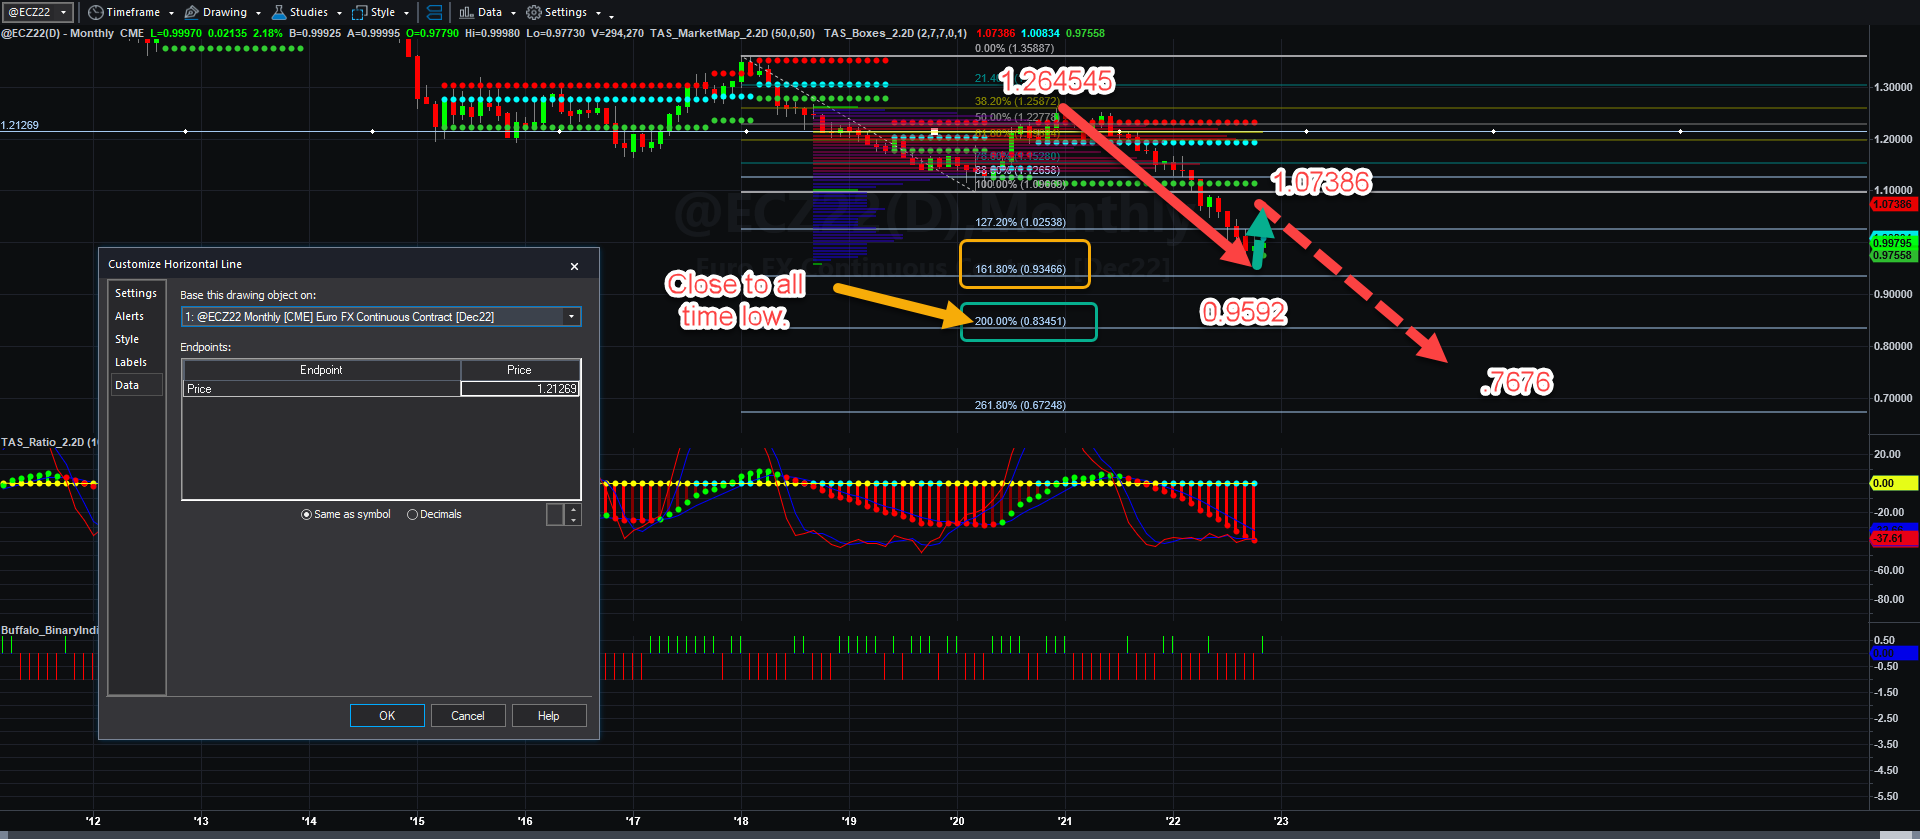
Assuming a monthly chart rally related to a recent pivot in prices above 0.9592 remains in place, it could rally and stop along the 38.2% retracement of the last down move from 1.26545. If it did and another symmetrical price move occurred because of dollar strength ( from continued rising rates) it could conceivably hit a new low of 0.7678. This could take a year to happen, but if US rates continue to rise beyond the “narrative” CPI as opposed to numbers used to calculate it in 1980, that target could be achievable. If not, it could stall out around 0.8345 which would nearly equal the all-time low for that contract.
What is truly the threat longer term is that BRICS+ will create their own market basket of commodities-or-precious-metals-based currency to accept payments, thus eliminating their need to price anything in U.S. Dollars. Now that Saudi Arabia has snubbed the US and decided to accept payment for oil in rubles, America will have more limited ability to print money as there is no transactional value in transactions for commodities, particularly oil. If that happens, the USA will have to pay higher interest rates to borrow money, since its currency is no longer attractive to hold.
We will learn how serious that problem will become in 2023 and beyond. Trust me, it WILL be a problem unless these policies are reversed. Will the mid-term elections in the US do that? I have no clue. As with trading, it depends on who shows up, and who cheats possibly. We will know soon enough.
These are just some of the major reasons why I think we are a long way from any kind of constructive bull market in MNQZ22 or anything else. We will see bear market rallies, but as far as another major bull run, we will need major structural repair of fiscal policy, monetary policy, and monetary construction before that happens.
Conclusion:
Anything can happen, including a bull market rally in the daily charts perhaps to 11588, or even as high as perhaps 12966 in the coming weeks. I still think the headwinds ahead for our economy will prevent any appreciable rally from happening until the issues related to government throttling of the economy are ended to extended. That jury is STILL OUT!
As always, thank you for supporting this blog! I will return soon to add more data and commentary. If you have questions, leave them in the comments. Have a great week, everyone!

